 AION
Research / Retail Investor Field Guide
Lesson 9 of 11 | Financial Statements and Governance
Forensic Accounting: Read the Opinion and Notes
An auditor opinion states the auditor's conclusion about the financial statements under the applicable standard. Related-party notes disclose transactions with connected entities. Cash flow shows cash generated or used by operations.
What to look at
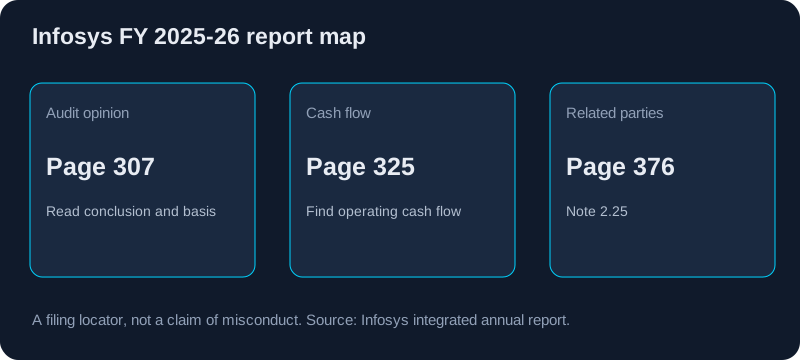
The Infosys consolidated report for the year ended 31 March 2026 has an auditor opinion at the start and related-party transactions in Note 2.25. Read the opinion and the note separately, with their reporting period. This is a reading example, not an allegation.
What the evidence establishes
A qualification, emphasis of matter, cash-flow divergence or related-party amount can raise a question worth checking against management's explanation and prior periods.
What it cannot establish
No single note proves fraud or predicts price. An unmodified opinion is not a guarantee that every risk has been found.
Observation exercise
On two days, locate an annual report's opinion and its related-party note. Record the reporting period, the auditor's exact opinion type, the transaction categories and where the operating cash-flow line appears.
When to stay away
Stay away from an unresolved material accounting question that you cannot explain from the primary filing.
Limitations
An unmodified opinion is reasonable assurance, not a guarantee. Related-party transactions require reading amounts, terms, approvals and comparison with prior periods. The presence of a related-party note is not itself a red flag.
Primary sources and related research
- Infosys consolidated annual financial statements, FY 2025-26
- Infosys related-party disclosure archive
Related research: What the Consolidated Account Statement Shows.